Europe

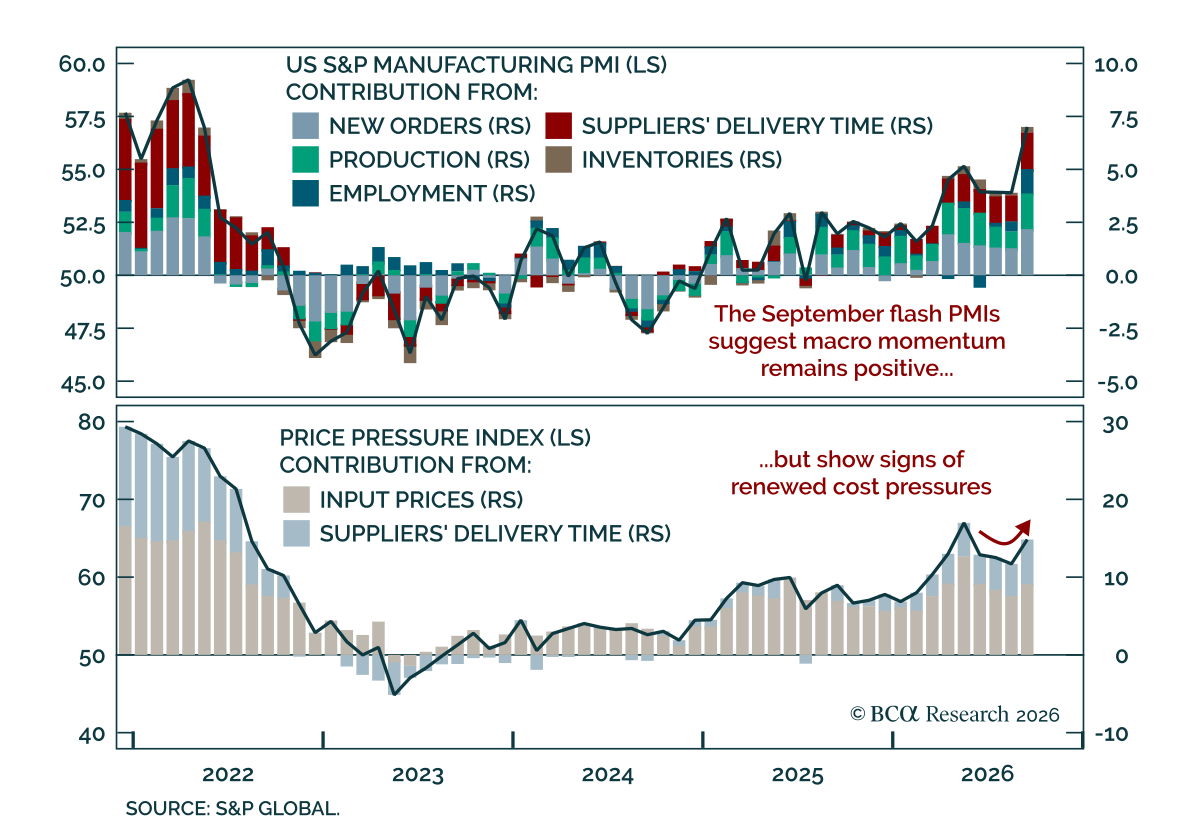
Europe was shunned while AI could do no wrong. That trade is looking tired. Falling energy prices and cracks in the AI boom favor rotating out of US equities and into cheaper European stocks. Favor defensives: Europe can win the relative race even if both markets fall.

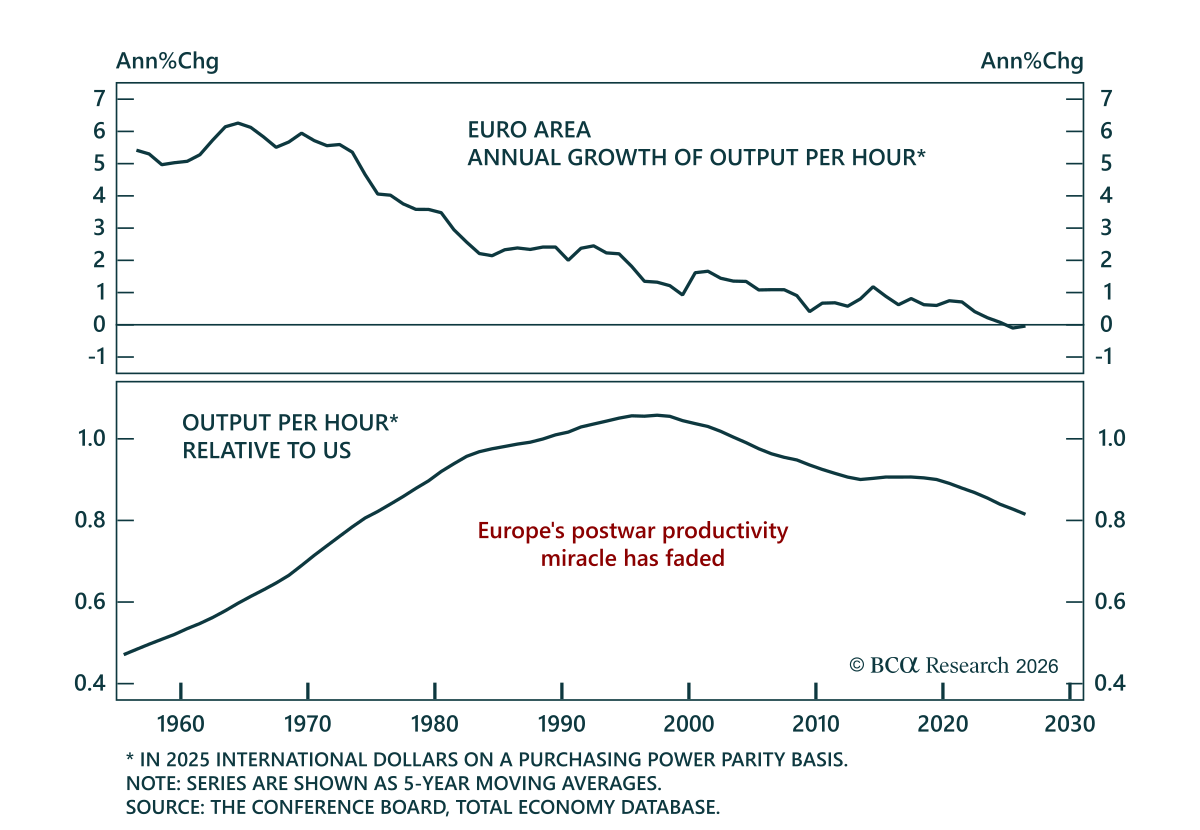
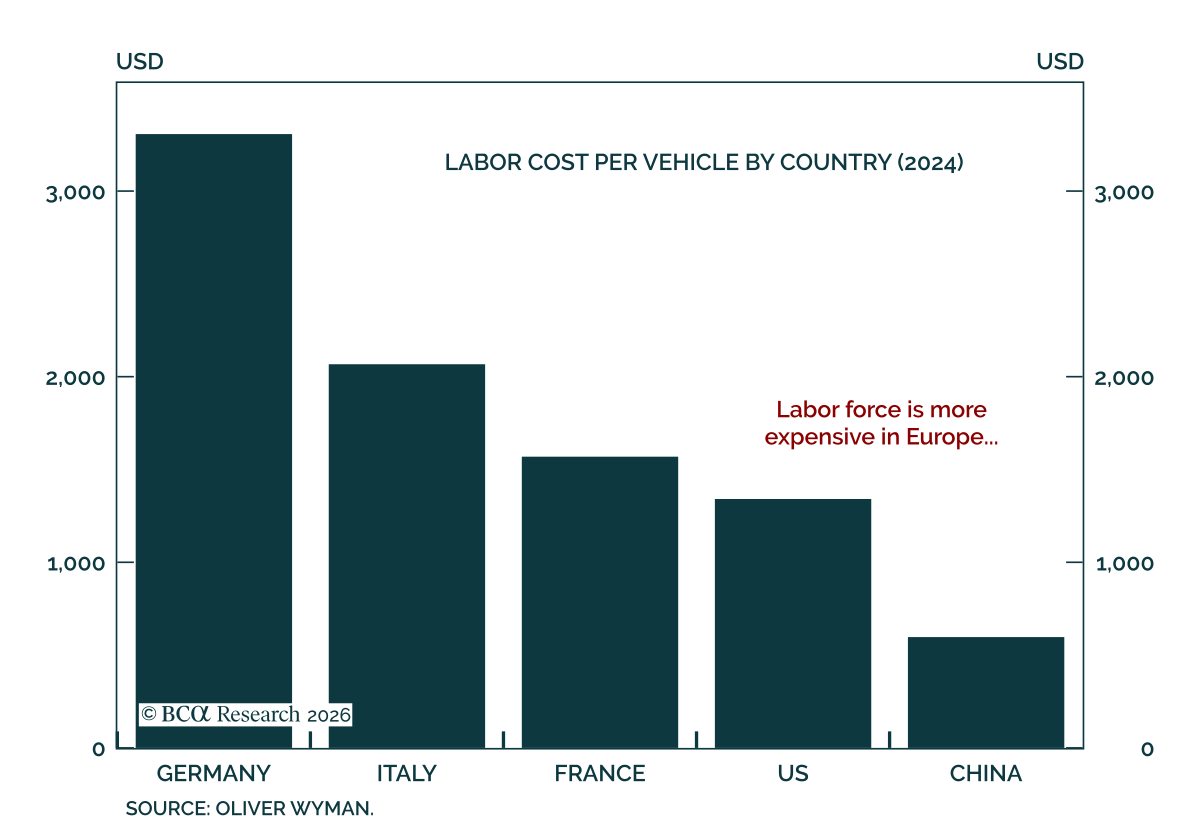
Europe faces deep structural problems. Dismantling large parts of the welfare state might be necessary to rectify these problems, which is unlikely to happen before there is a major crisis. Until then, investors should “sell Europe” on any rallies.

US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.

In this screener report, we explore opportunities in high-quality Tech, European integration winners, and selective US cyclicals in Industrials and Materials.

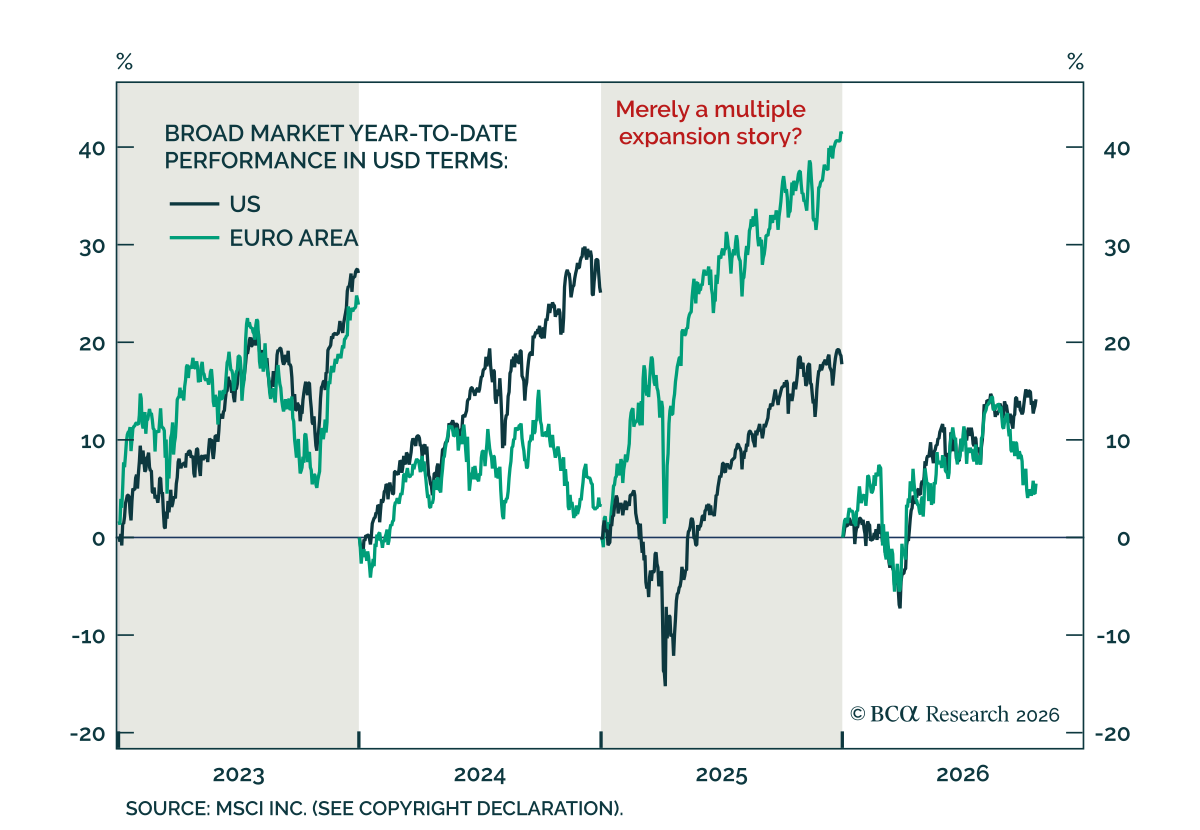
Europe has 99 problems, but the paucity of bearish views about the Old Continent is not one of them! And yet, somewhat shockingly, European assets have outperformed US assets over the past two years. Sure, markets make mistakes. But the macro graveyards are littered with investors who thought they were smarter than the markets. In this report, we suggest that Europe is on a cusp of significant structural reforms that will unlock value in its services sector. And that while many of the challenges are real, they’re either well understood or priced in.