BCA Indicators/Model

MacroQuant recommends a slight underweight to equities and an overweight to bonds and cash. The model is bullish on the US dollar, negative on gold, very negative on copper, and neutral on oil.

GBP offers attractive carry today, but the market’s aggressive rate hike pricing is likely to turn into a headwind within 12 months. Our latest Currency Chartpack examines the valuation, growth, rate, and policy drivers of the pound, showing why the long-term outlook is less rosy than near-term data implies.

The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.

We review our Model Bond Portfolio performance for Q3 and look ahead as energy prices continue to drive fixed income markets. Balanced labor markets point to a mild tightening cycle, creating opportunities in government bonds and credit, while inflation-linked bonds continue offering protection against persistent energy risks.


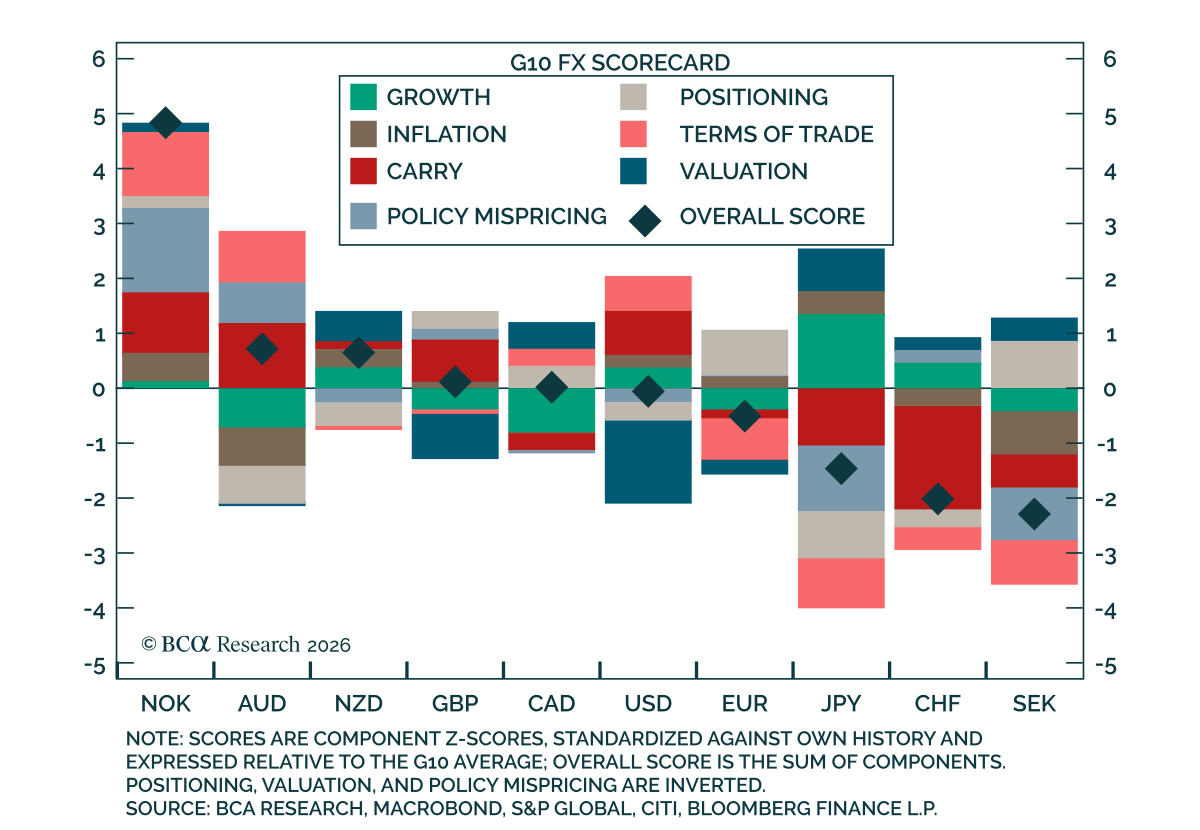
Our G10 FX cyclical scorecard still favors high-carry currencies over low yielders, suggesting patience should continue to pay. We break down the factors driving each currency and highlight the most appealing relative-value opportunities.

MacroQuant recommends an underweight to equities and bonds, counterbalanced by a significant overweight to cash. The model is very bullish on the US dollar, slightly negative on gold and copper, and positive on oil.

Global capex is driving the strongest industrial cycle since 2021. The US is best positioned to capture the gains and to weather near-term risks, supporting widening real-rate differentials and favoring continued upside in the dollar in the coming months.

Central banks have begun a mild tightening cycle as elevated energy prices raise concerns about second-round inflation effects. We use BCA’s Central Bank Monitors to test whether hawkish market pricing is justified and identify tactical opportunities across global bond and currency markets.