Skip to main content

AI and Markets

Our Portfolio Construction strategists remain bullish on risk assets but express that view through barbells across the portfolio. October looked cataclysmic from the headlines, with neocloud debt spreads spiking and Alphabet suffering its worst one-day loss…

Despite October’s AI selloff, indices remain resilient thanks to historically high dispersion. We remain bullish, but with barbells across the portfolio. Hedge equity with equity: Overweight Technology and Healthcare. Remain overweight high yield. Downgrade linkers and upgrade nominal bonds. Upgrade tail risk protection to overweight as a hedge against a resumption of the war.
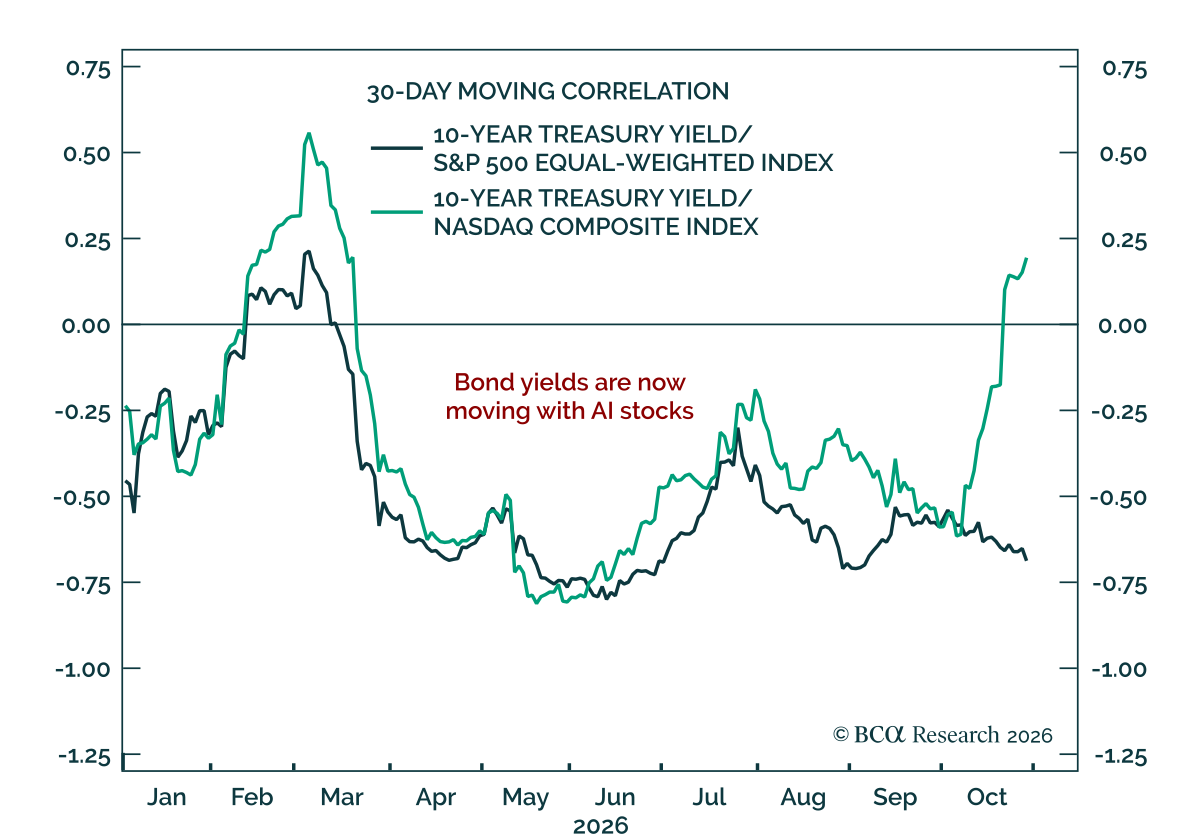
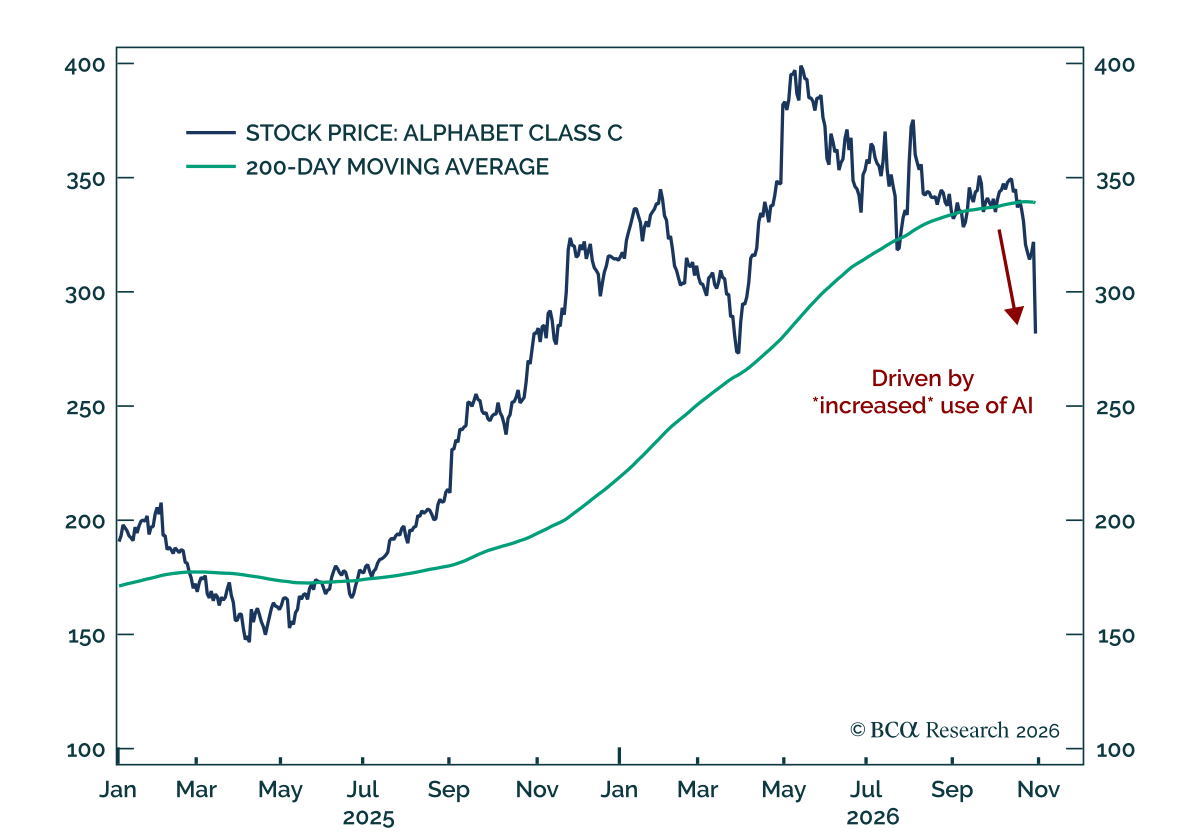
AI equity performance has replaced oil as the main driver of US Treasury yields, setting up a rotation out of AI stocks into the rest of the market. Our Chart Of The Week comes from Ryan Swift, our Chief US Bonds Strategist. Bond yields now track AI stocks…
Google’s disappointing earnings results are company-specific and not a warning sign about AI demand. Google and Microsoft reported earnings on Thursday. The former’s stock price fell sharply in response, whereas the latter was mostly flat. There are two…
Anthropic filed Form S-1 with the SEC on Monday, heightening investors’ focus on the firm’s IPO that will likely occur before the end of the year. The filing comes at a time when investors are vigorously debating whether the pace of AI-related CAPEX is too…
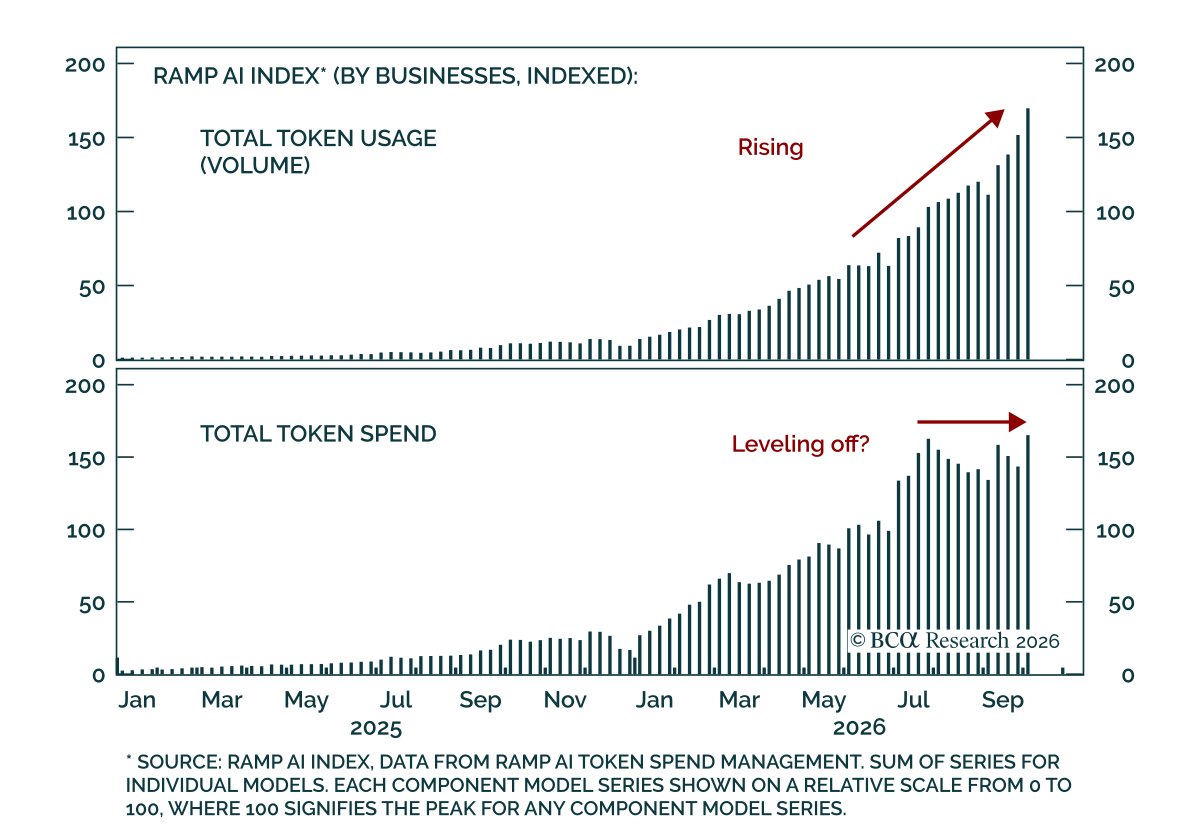
Tech stocks were spooked last week by signs that AI model developers may not be growing as quickly as previously thought. Tech-related stocks performed poorly last week, seemingly in contrast to fundamentals. The NASDAQ fell over 4%, despite a modest rise in…
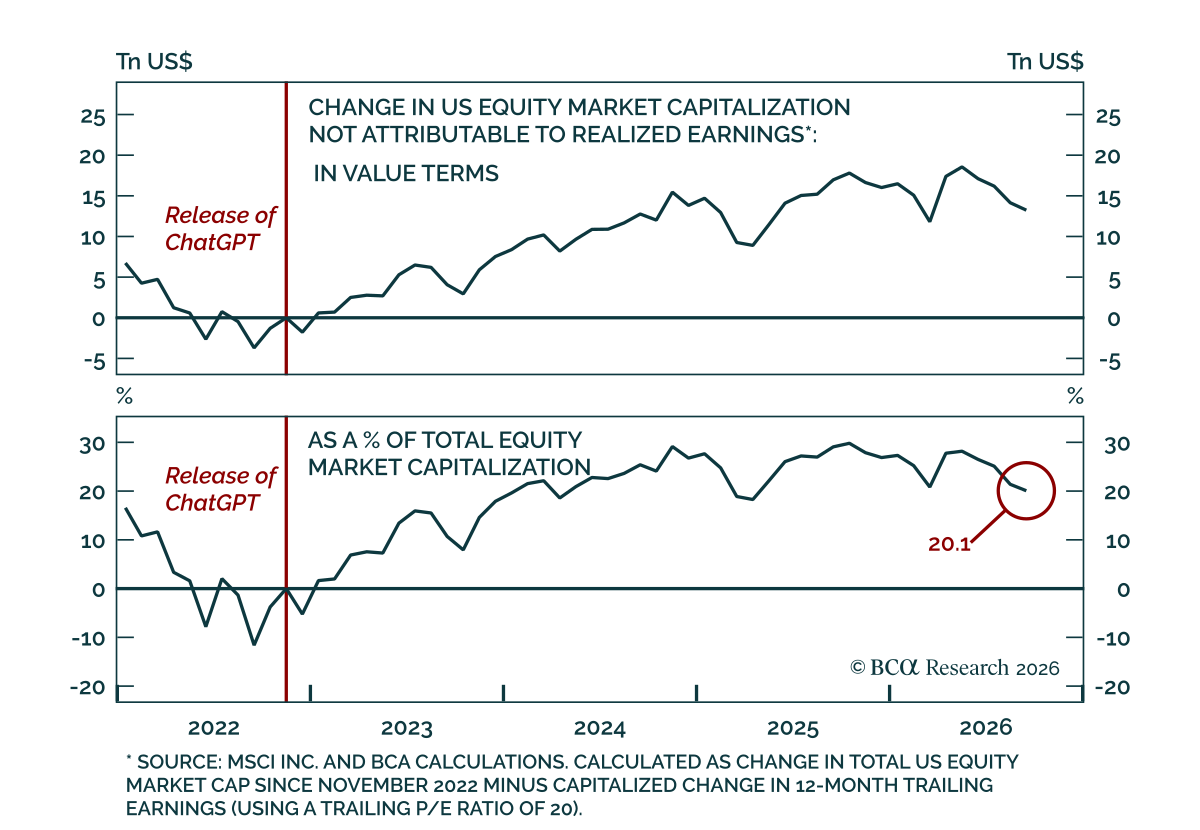
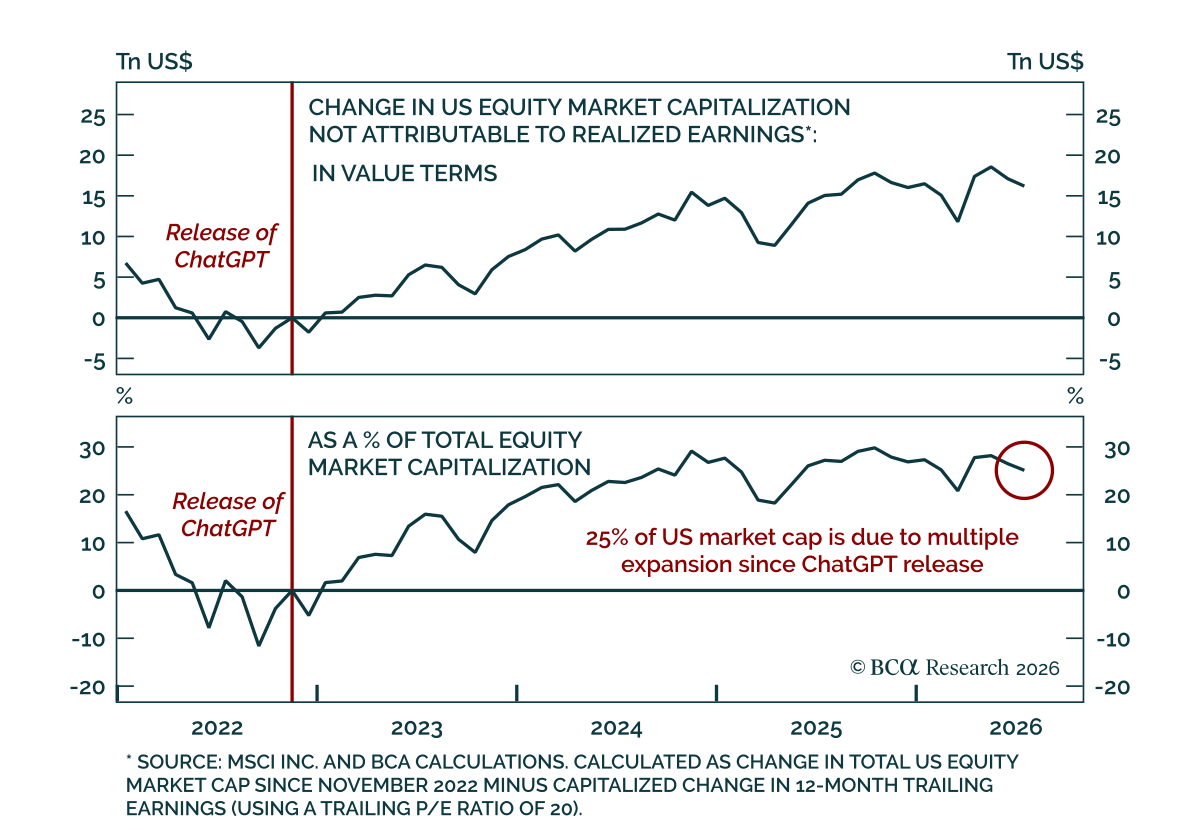
AI-driven multiple expansion has sharply compressed the equity risk premium, leaving US equities with little cushion if adoption, demand, or earnings disappoint. Our Chart Of The Week comes from Jonathan LaBerge of our Essentials and CoreMacro platforms.…

An acute shortage of AI hardware will support tech stocks into year-end. However, AI companies may need to ultimately generate $10 trillion per year in revenue to justify their capex. Barring a massive increase in productivity growth, this will be very difficult to achieve. Despite today’s Treasury announcement of upsized buyback operations, bond yields are likely to remain elevated over the coming months. Rising crack spreads have reduced the demand for crude, which is not encouraging for global growth. On the FX front, recent intervention to support the yen will probably be insufficient, but there is significant long-term upside for the currency.
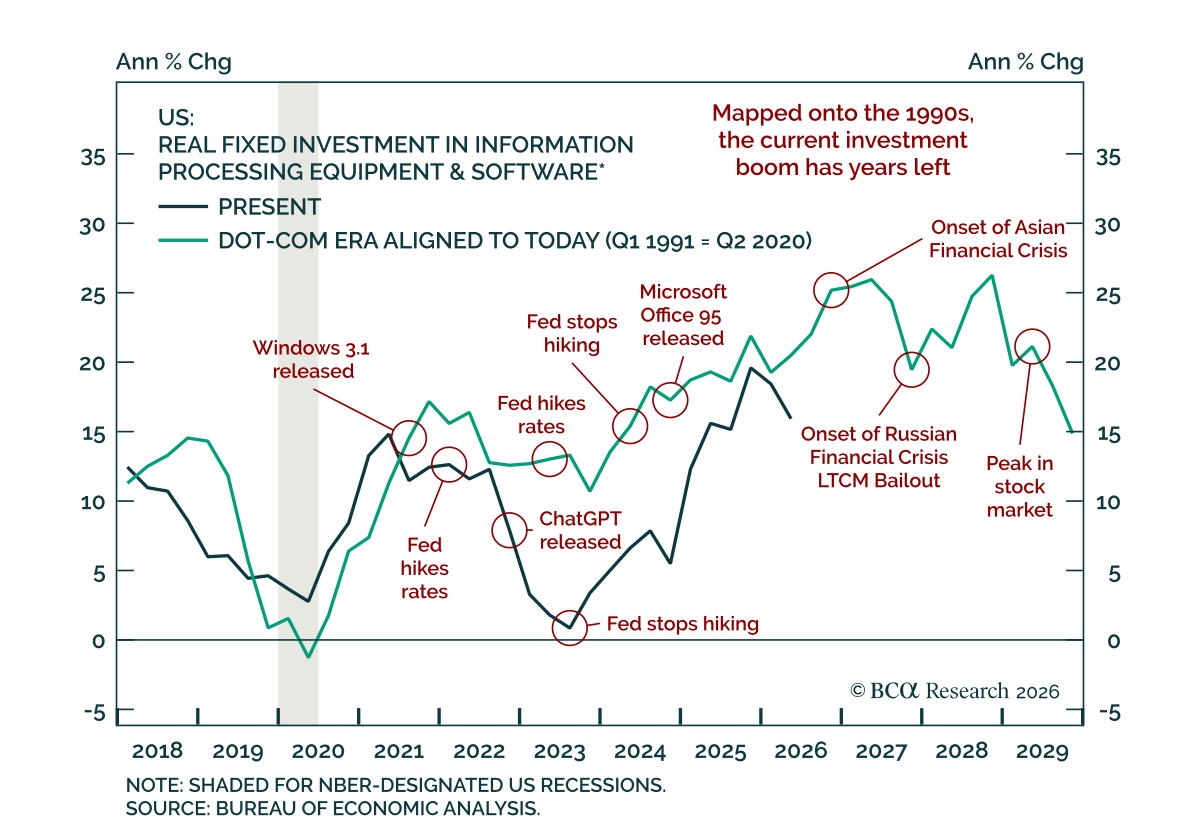
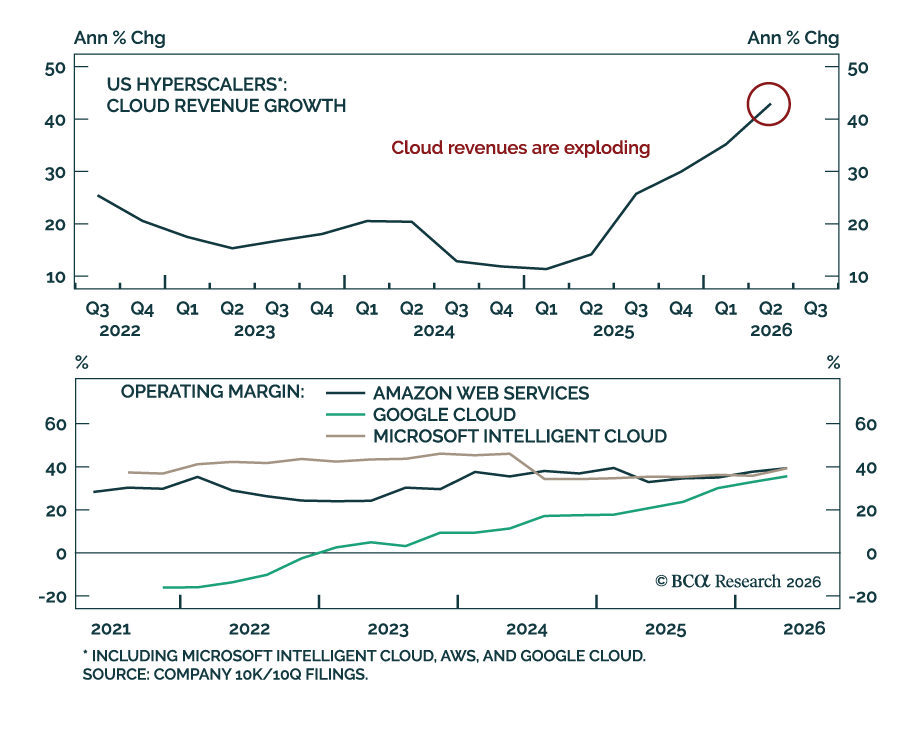
Our GeoMacro strategists stay overweight equities, expecting the bull market to run further. The July earnings season has confirmed the AI capex engine is still running hot, just as Iran-US tensions peaked. Cloud revenue at the three largest hyperscalers grew…
Our Global Asset Allocation strategists see the return on AI capex now becoming visible in reported results, clearing the way for the bull market to move higher. Investors have stayed deeply skeptical about the profitability of the buildout, yet Q2 earnings…