Gov Sovereigns/Treasurys

US Treasury yields have fallen below our fair value estimate as investors rotated out of AI equities and into fixed income. We lay out why near-term inflation risks argue for a rebound, and the tactical trades we initiate to position for it.

The Fed will hike rates at a pace of 25 bps per quarter until either falling inflation or tighter financial conditions cause it to stop.


EM local bonds face near-term turbulence from rising inflation, global risk aversion, and currency weakness. Use the sell-off to build exposure: medium- and longer-term fundamentals remain favorable.

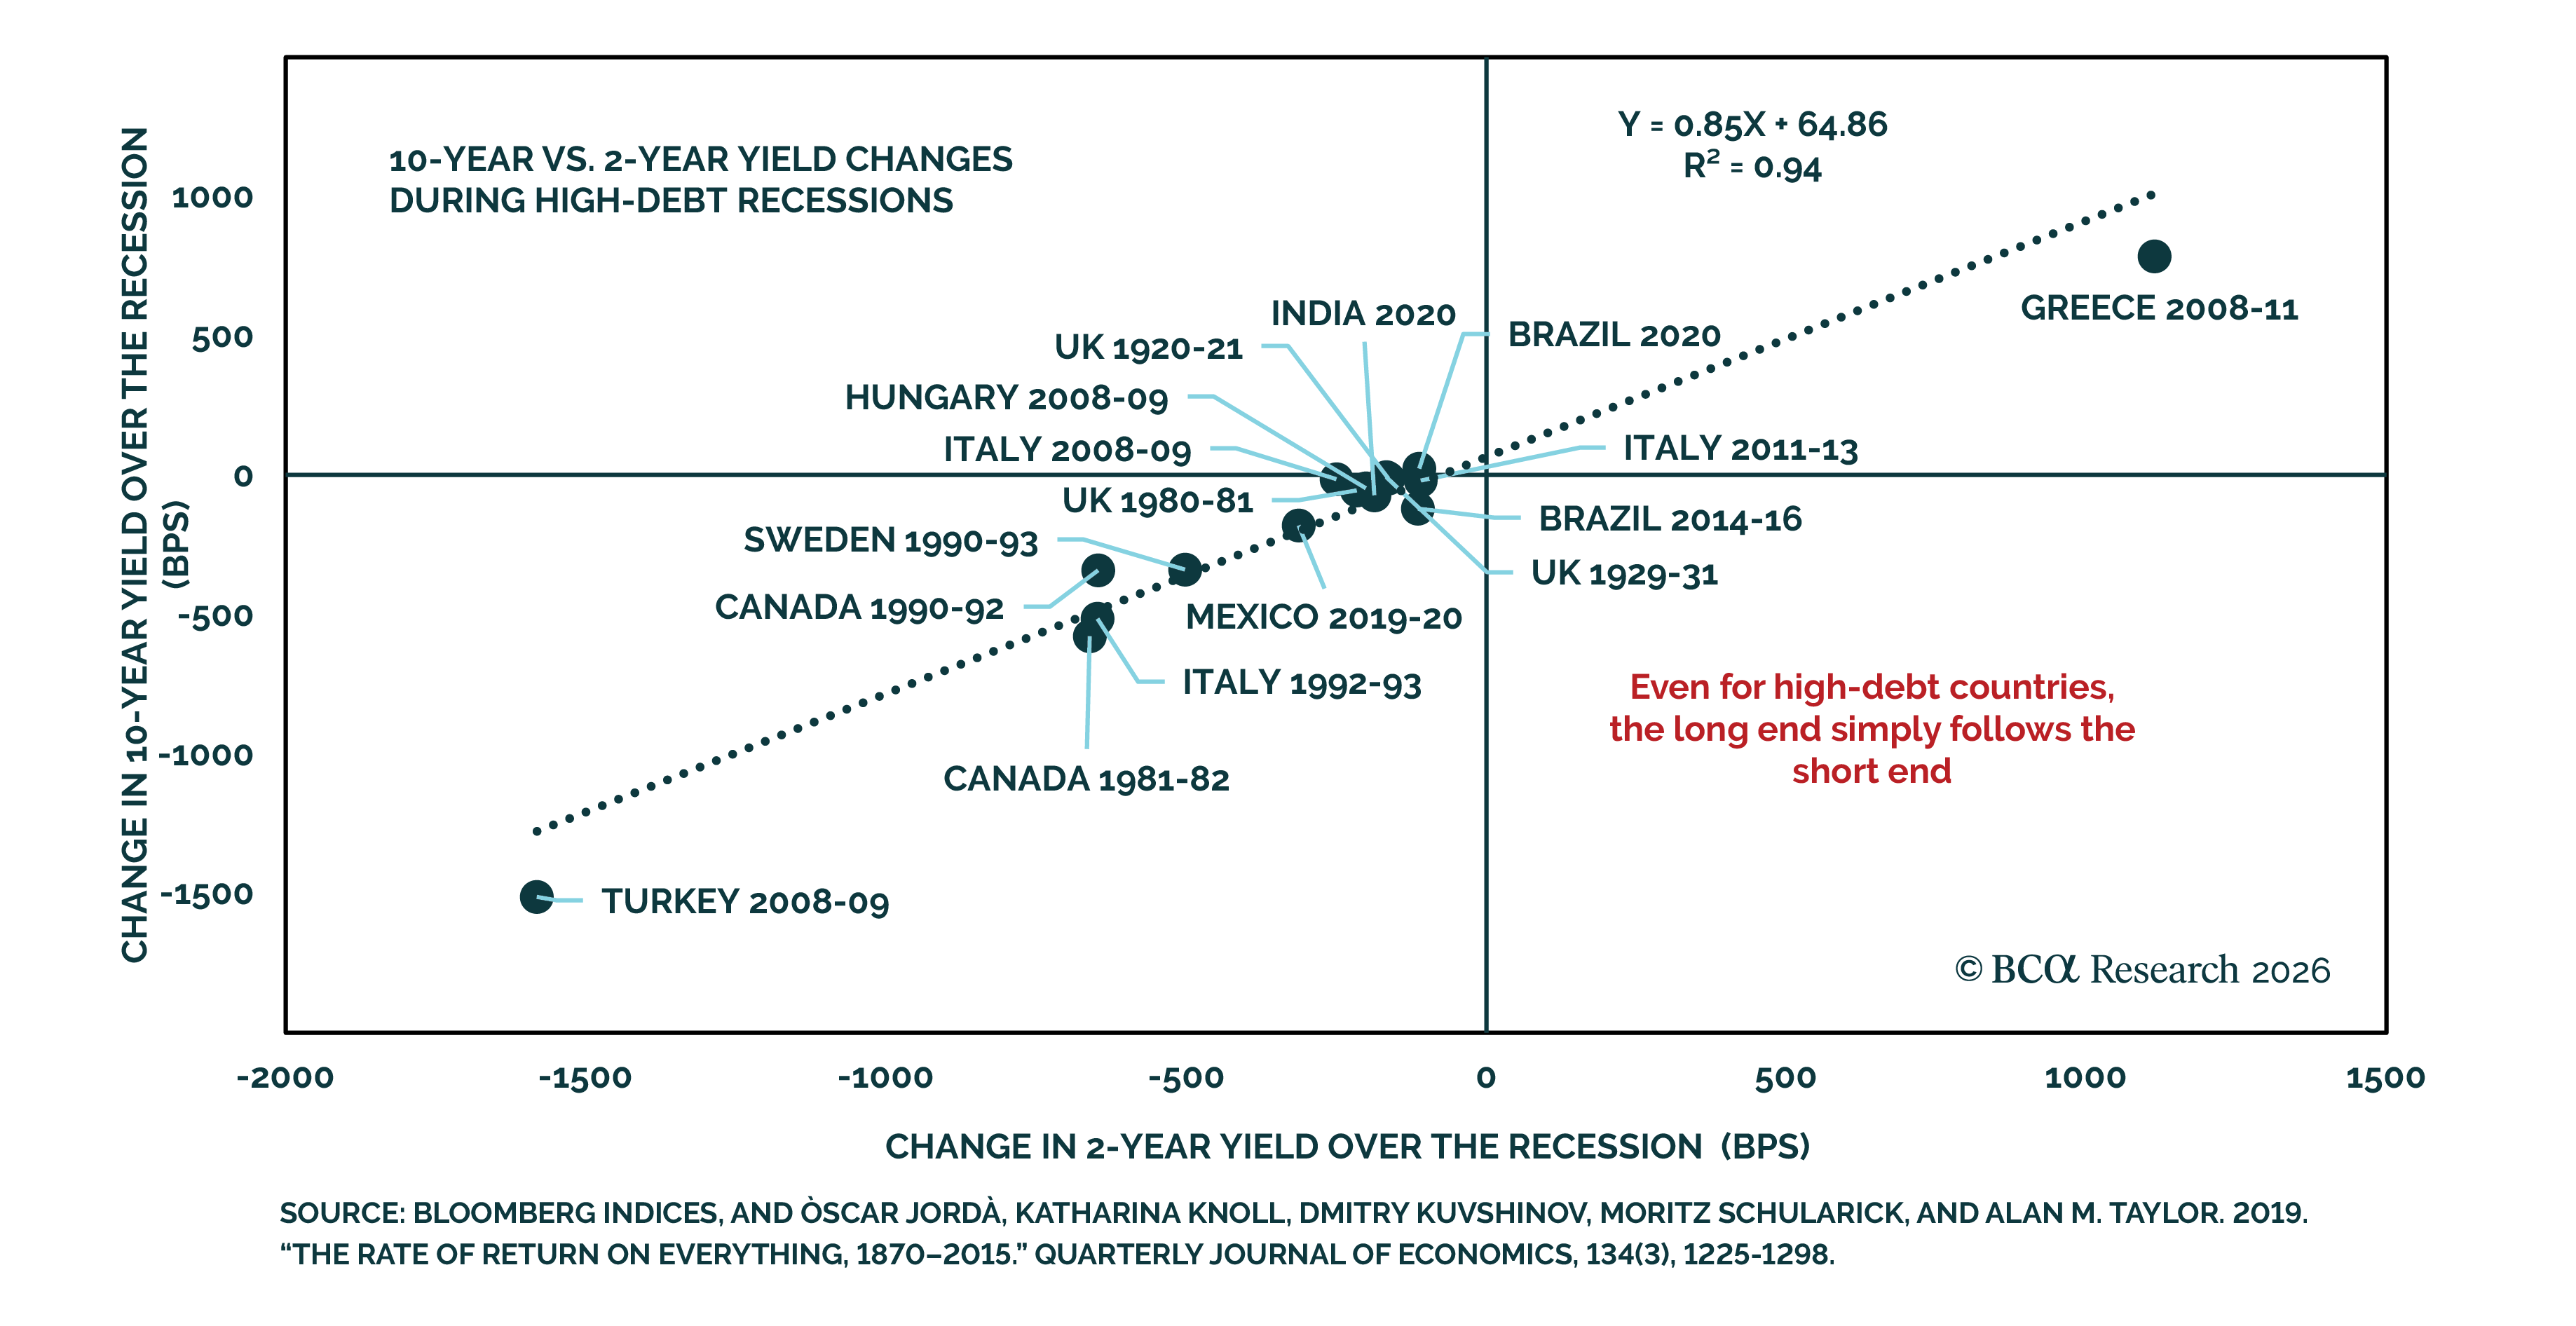
History suggests central bank policy determines how bonds behave in recessions, even for high-debt countries. The Fed should be able to cut into a slowdown, making Treasurys an effective equity hedge… for USD-based investors. Foreign investors will see currency depreciation erase their gains.

We review our Model Bond Portfolio performance for Q3 and look ahead as energy prices continue to drive fixed income markets. Balanced labor markets point to a mild tightening cycle, creating opportunities in government bonds and credit, while inflation-linked bonds continue offering protection against persistent energy risks.


US bonds will likely continue selling off until tighter financial conditions – most plausibly a double-digit decline in the S&P 500 – cool nominal growth. Higher discount rates will threaten US equity valuations before earnings weaken. AI stocks will peak well ahead of AI capex. Remain downbeat on EM stocks.

The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.