 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.

This report looks at the likely path for the dollar and bond yields over the next 6-to-12 months.

The bond market priced out a lot of recession risk after this morning’s employment report, and the 10-year Treasury yield has moved back into the Soft Landing Zone. We assess the data and consider whether we need to change our cyclical positioning.

Our Portfolio Allocation Summary for October 2024.
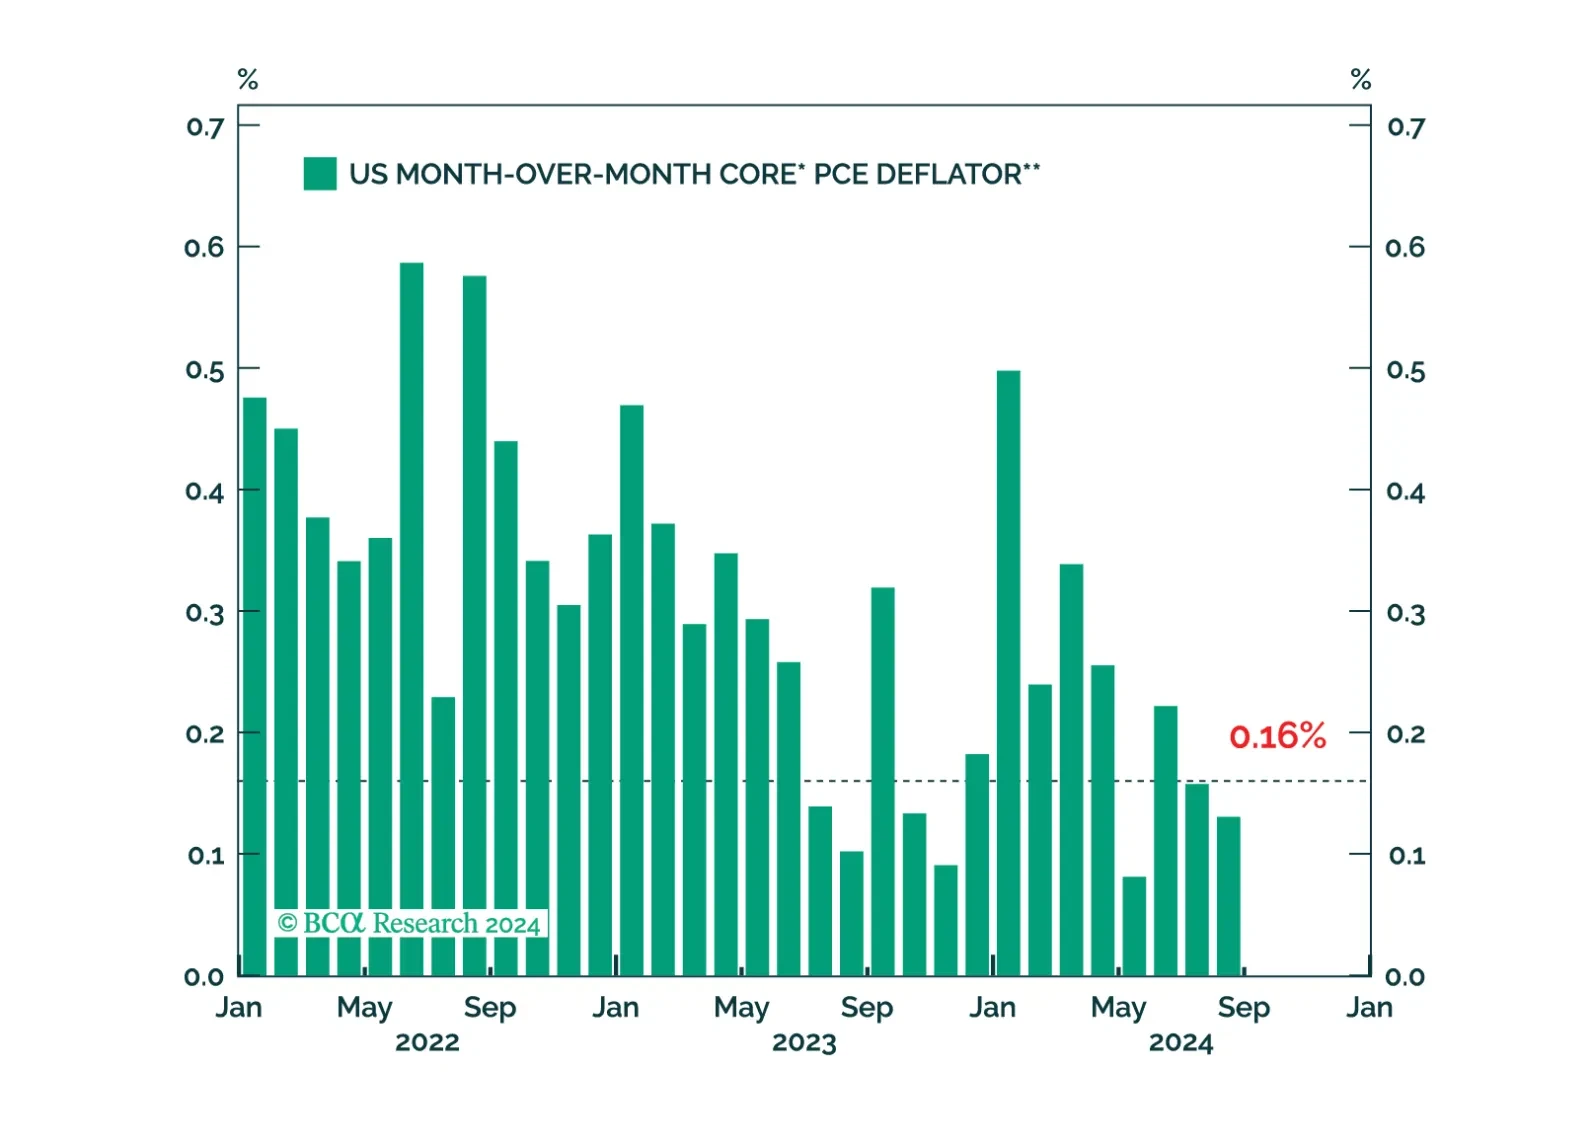
We consider the possibility that lower interest rates could lead to an increase in household borrowing, prolonging the economic recovery.

This insight parses through the RBA’s latest policy decision, and makes recommendations on whether to expect any rate cuts in 2024, and beyond.

We update our corporate default rate model and consider the implications for corporate bond spreads.


The ECB will cut rates once more this year; however, markets underprice how far it will ease next year.
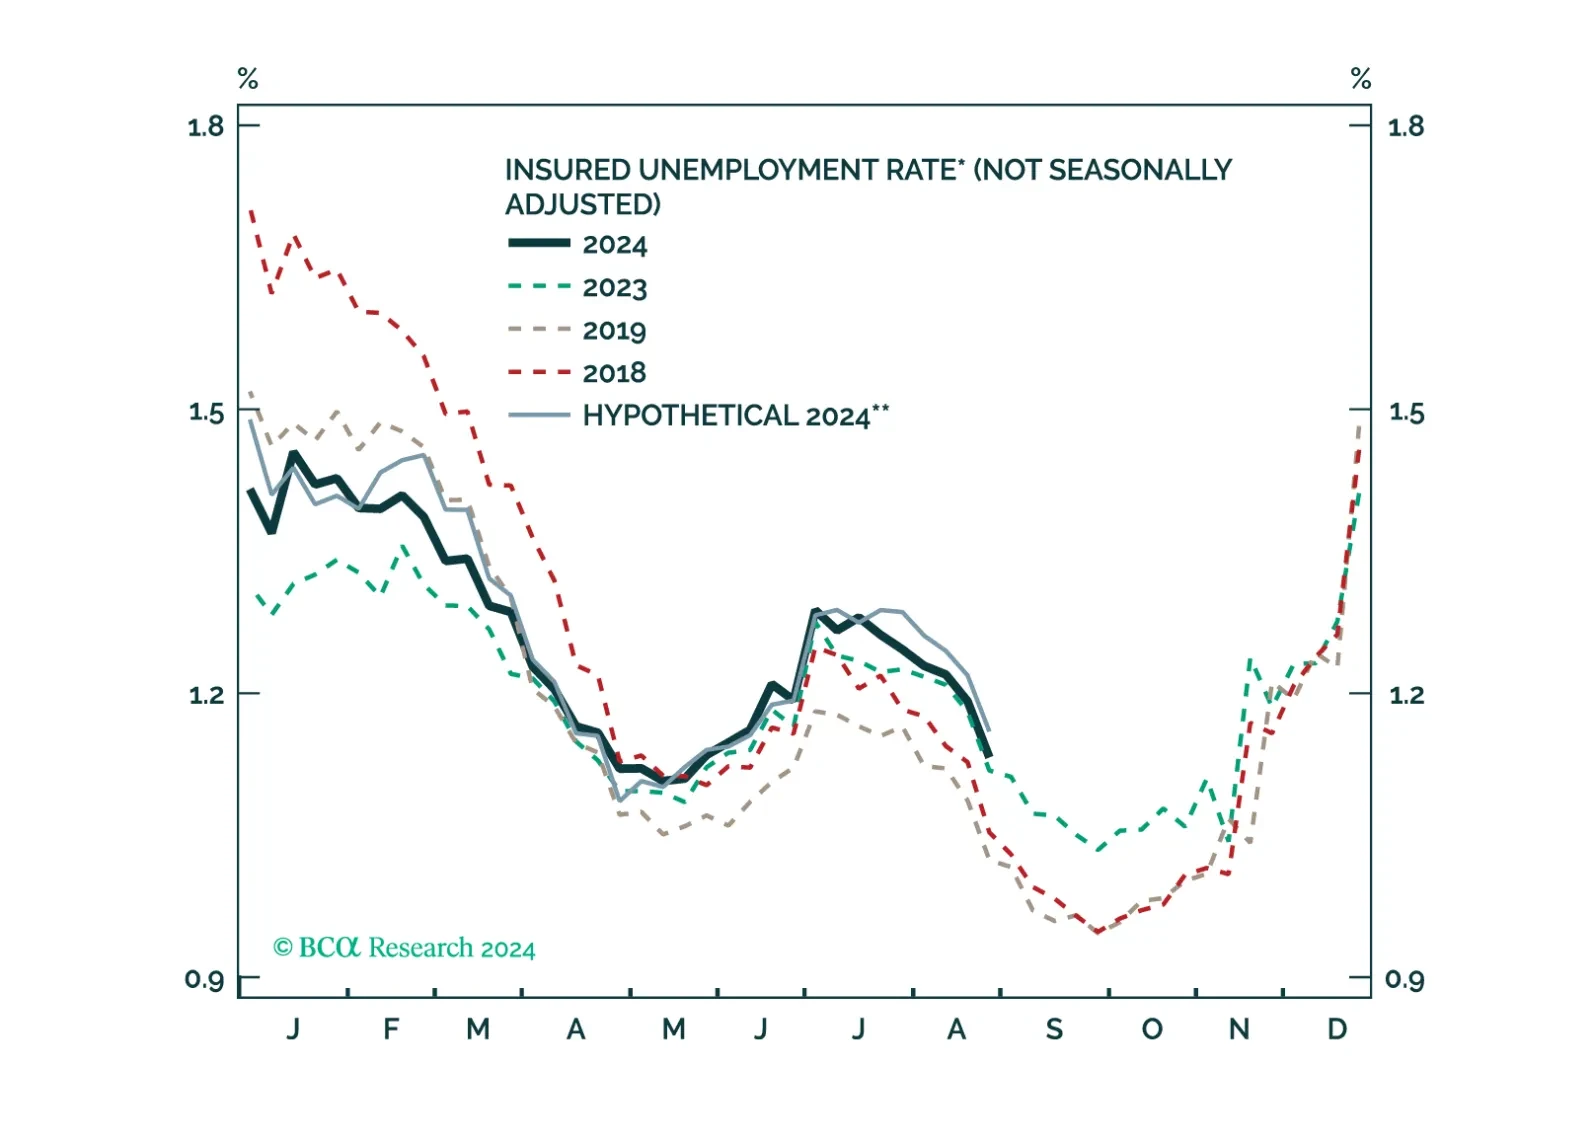
Some thoughts on this morning’s US claims report and a preview of next week’s FOMC meeting.